
Blockchain protocols and their role in security
What are blockchain protocols and how do they protect data?
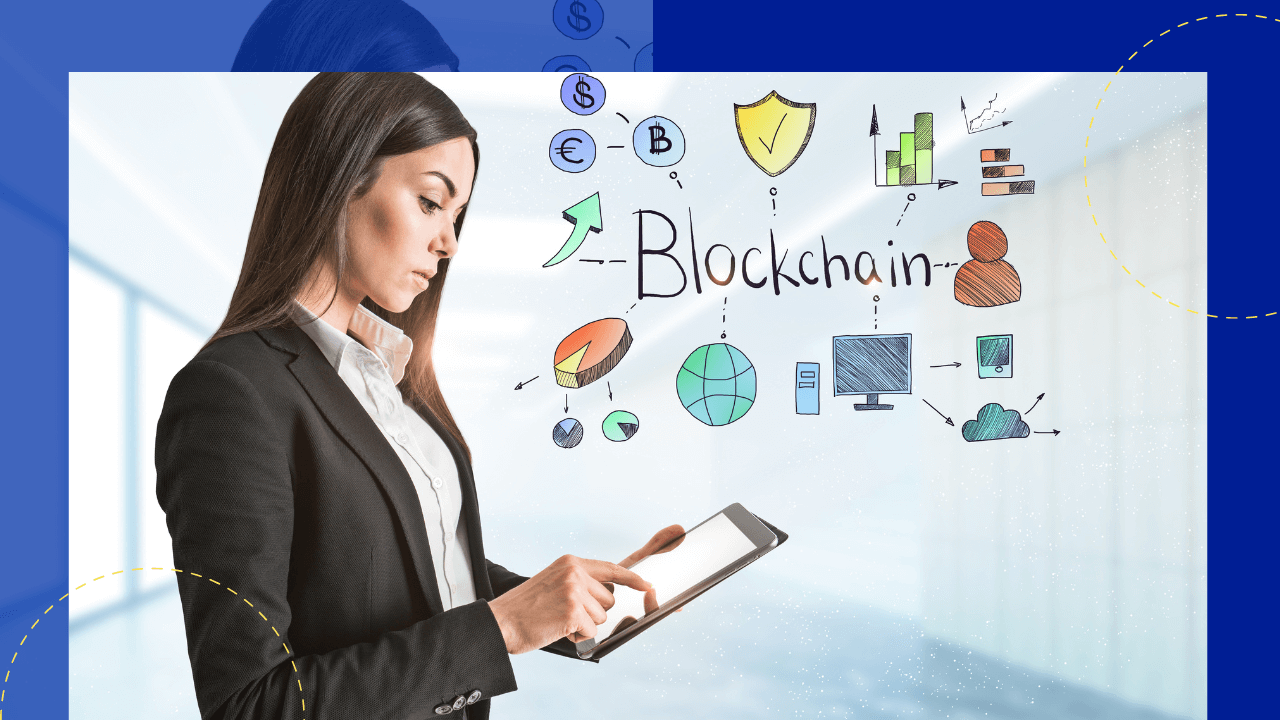
Blockchain protocols are the rules that keep a blockchain network secure, transparent, and very hard to tamper with.
- They set how data is stored, shared, and checked across the whole network.
- They remove the need for one central authority, so trust is built in.
- They guard digital money and records against fraud and hacking.
Blockchain protocols now sit at the heart of digital security. Technology keeps growing fast, and new tools appear every year. However, this quick progress also opens fresh ways to attack data. So blockchain protocols help stop that. For example, they protect user data and digital money like cryptocurrencies. As a result, a strong security system matters more than ever.
The rise of cryptocurrency
Cryptocurrency works as both a payment method and an investment. Its value moves with the global economy. So it can be traded, mined, and burned. In short, prices rise and fall with supply and demand.
Bitcoin arrived in 2009 as the first public cryptocurrency. At first, people only mined it and rarely traded it. Still, it grew so fast that many early buyers became rich. Today, the market holds many different coins.
These high-value coins are what blockchain protocols protect. Because they are worth so much, they draw attackers. For example, they face ransomware that puts investor privacy at risk. Meanwhile, this shift also challenges old banking systems with a decentralized network.
All about blockchain protocols
A blockchain protocol acts as a safety layer. It protects the data, transactions, and money tied to cryptocurrencies. In simple terms, protocols are the base of blockchain technology. Building on these protocols takes scarce talent, which is why many teams turn to blockchain development outsourcing for engineers who are hard to hire in-house. So they set the structure and the way people interact on the network.
Blockchain protocols are not just for cryptocurrency. For example, you can see similar ideas in web services like email. Emails move through many sets of protocols to keep messages safe.
What makes these protocols important is their power to decentralize cryptocurrencies. Without a central hub, the network runs on trust between members. As a result, companies can keep a secure and private setup. This same idea now powers blockchain in online retail and many other tools.
Five components of blockchain protocols
Just as HTTP controls how the internet talks, blockchain protocols drive transparency, immutability, and decentralization. So they shape how the digital world stays safe.
Hyperledger
Hyperledger launched in 2015 as an open-source enterprise framework. It uses a permissioned blockchain, yet any skilled member can help build it. Because it draws from many frameworks, it gives a shared guide for enterprise blockchain work.
Corda
Corda is also open-source and built for business. It uses consensus algorithms to check and confirm transactions for members. It earned backing from R3, a banking consortium. As a result, most of its users come from finance and banking.
Multichain
Multichain takes a different path. It runs a private blockchain for a company’s financial transactions. Its goal is to keep records safe inside the group. So only verified members can make transactions here.
Quorum
Quorum is an Ethereum-based blockchain. It began as a project from the well-known cryptocurrency. At first, it only added privacy and transaction support for Ethereum users. However, it now handles network management, consensus voting, and better speed. Today, many financial firms rely on it.
Enterprise Ethereum
Ethereum ranks among the largest cryptocurrencies worldwide. It is a public blockchain with features like smart contracts and dApp building. Because businesses needed more privacy, the team built Enterprise Ethereum. So this version is private and permission-based for safer transactions.
Must know blockchain protocol
Protocols set the rules that confirm transactions on a blockchain. So these core ideas are worth knowing.
Distributed Ledgers
Distributed ledgers are databases shared across many sites and groups. They let transactions go public, copy, and reshare in seconds. In short, a blockchain is one type of distributed ledger.
Smart Contracts
Smart contracts share stored data across networks. They run and record events on their own once all parties agree on the terms. As a result, they cut manual steps and speed things up.
Coins and Tokens
A blockchain protocol needs digital assets to work, and that is the role of coins and tokens. They reward the people who keep the network running. For some coins, they also show a person’s share or ownership. Their jobs look alike. However, coins are more basic, while tokens sit higher up and run through smart contracts.
51% Attack
A 51% attack happens when one member controls more than half of a network. This is possible because many crypto projects rely on anonymous voting to reach consensus. The more coins a member owns, the more voting power they hold. So a bad actor could overspend or alter the network. As a result, it can also hurt a project’s good name.
Consensus Algorithm
A consensus algorithm helps a network agree on which transactions are valid. It builds trust and reliability between nodes. Because of this, blockchains use it for extra security.
Secure your network with blockchain protocols
High technology brings a high risk of hacking and data breaches. Blockchain protocols aim to keep these threats away. They set how data is built and stored across a peer-to-peer network. As a result, records stay clear and hard to change. Strong data security habits make this even more effective.
When your business lives online, these safety features matter. For example, the Bitcoin protocol changed digital payments. It let people pay safely without a central authority. To go further, pair blockchain with proven cybersecurity habits and solid cloud security. In addition, fields like finance and healthcare records now lean on the same tools.
Frequently asked questions about blockchain protocols
What is the main purpose of a blockchain protocol?
A blockchain protocol sets the shared rules for a network. It decides how nodes store, check, and share data. So it keeps every transaction clear and secure. In short, it builds trust without a middleman.
Are blockchain protocols only used for cryptocurrency?
No, they reach far beyond coins. For example, businesses use them for supply chains, contracts, and secure records. Many web services rely on similar rules too. As a result, their uses keep growing each year.
What is the difference between public and private blockchains?
A public blockchain lets anyone join and view transactions. A private one limits access to verified members only. Because of this, firms often pick private setups for sensitive data. Still, both types use protocols to stay secure.
How do blockchain protocols improve security?
They spread data across many nodes instead of one server. So there is no single point to attack. Consensus rules also confirm each transaction before it is added. As a result, tampering becomes very hard.
Can small businesses use blockchain protocols?
Yes, many tools now make this easier and cheaper. Small firms can use them for payments, records, and data safety. First, pick a protocol that fits your needs. Next, work with a trusted provider to set it up.






 Independent






